

An upcoming study by Nuvau Minerals (TSXV: NMC) on potentially restarting the historic Matagami base-metal operation in Quebec will extend the project’s mine life while reducing pre-production costs.
Nuvau is targeting November at the latest to release an updated preliminary economic assessment (PEA) for Matagami, replacing a May 2024 analysis, CEO Christina McCarthy says. A prefeasibility study could follow next year, with initial production potentially starting in 2029 after a new tailings facility has been built, she said.
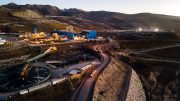
Toronto-based Nuvau acquired Matagami from Glencore (LSE: GLEN) in March, gaining control of a camp that contains the Bracemac-McLeod mine, the Caber deposits and other historic deposits, plus existing infrastructure. A processing plant and tailings facility were excluded from the deal, though Nuvau has a 24-month right to buy the assets.
“This PEA that we’re putting out this fall isn’t the typical arm-waving PEA that a lot of juniors put out,” McCarthy told The Northern Miner in an interview. “It’s going to be more advanced. We have a fully permitted mine. There’s a fully permitted mill right there on site. We just have to build the tailings facility, which takes about two years. That’s the longest timeline.”
Based on an 8% discount rate, Matagami has a $115.9-million (US$82.2-million) net present value, a 20% internal rate of return and a three-year payback, according to the 2024 PEA. Capital expenditures were pegged at about $172 million, with an estimated mine life of 9.5 years.
Fourth mine
A significant climb in metals prices has lifted the economics of a Matagami restart beyond the 2024 PEA’s estimates, McCarthy says. Operational changes have also made the investment more compelling, she adds.
“We intend to add a fourth mine into the production profile,” McCarthy said. “We’re targeting around 13.5 years of production. We’re targeting the same three-year payback, but at a much lower capex.”
Some of the projected savings come from a decision to prioritize restarting the mothballed Bracemac mine, which was shut down by Glencore in June 2022 after about nine years of operation.
“Bracemac is ready to go,” said McCarthy.
“There’s not a lot of initial capex to get Bracemac back into production, so we are going to take it and put it right in the front of the production profile. It will be the first mine of the four to go into production and that will defer so much capital that our initial capex, instead of $172 million, is going to be closer to $100 million.”
Gold targets
Located about 800 km north of Montreal, Matagami sits on a 1,380-sq.-km land package in one of Quebec’s most prolific mining districts.
It’s sandwiched between the gold-bearing Sunday Lake deformation zone, which hosts Agnico Eagle Mines’ (TSX, NYSE: AEM) Detour Lake gold mine, and the Casa Berardi deformation zone, which hosts Orezone Gold’s TSX, ASX: ORE; US-OTC: ORZCF) Casa Berardi mine and the past-producing Selbaie property.
Only a fraction of Nuvau’s land package has been explored. What’s more, it’s never been explored for gold – an omission that the developer has begun to rectify.
Last month, Nuvau released initial assays from summer drilling at the property’s Thundermine target. They included hole TH-26-08, which cut 114 metres of 0.26 gram gold per tonne from about 260 metres downhole. It also cut a standout interval of 4.4 metres grading 138.87 grams gold from 383 metres depth.
“We straddle the deformation zones. I think there’s great potential for us to make a big discovery there,” McCarthy said.
“This is a massive property, and less than 5% of this entire land package has been explored for base metals and never systematically explored for gold, until now. Right now, we are refining the targets because this property is so target-rich. We have over 80 targets just in one zone.”
Processing mill
To restart Matagami, Nuvau will need a processing plant. It eventually aims to buy the site’s shuttered mill – but only after Glencore has submitted a closure plan to the authorities, which will need to approve the separation of the building and its environmental liabilities, McCarthy says.
“They have until July 2027 to submit their closure plan, which is fine because it works in our timing,” she said. “So getting to production could take two years in total – let’s say by early 2029.”
Nuvau’s size ensures that Matagami will get the proper attention it deserves, McCarthy insists.
“Glencore needed massive tonnage, a massive discovery to be able to justify continuing to work here, and they didn’t have it,” she said.
“I always say that the table scraps of majors end up being company-makers for juniors. I’m happy with a few deposits that we can put into a production profile and just continue to run this mill like a sewing machine for decades.”


Be the first to comment on "Nuvau sees lower capex for Matagami"