
Endeavour Silver (TSX: EDR; NYSE: EXK) puts the initial cost of building its Pitarrilla project in Mexico at $585 million (C$837.5 million) — just as the metal has slipped below the $50 per oz. that the company assumed in its feasibility study.
Spot silver traded at $42.58 an oz. early Friday. At $40 silver, the project’s after-tax net present value would fall to $423 million from $736 million at $50, using a 5% discount rate. The corresponding internal rate of return would drop to 12% from 16.4%, the Vancouver-based producer said in study results released after markets closed Thursday.
Pitarrilla “adds an advanced stage, long life growth asset, capable of being funded internally with upside opportunities ahead,” TD Securities mining analyst Wayne Lam said in a note late Thursday. “We view the project further positioning Endeavour favourably within the silver space in transforming the portfolio, complementing the brand new Terronera and recently acquired Kolpa mines.”
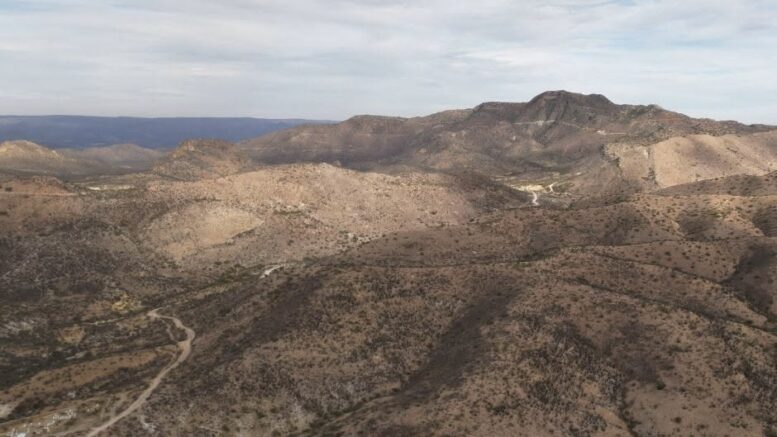
Located about 950 km northwest of Mexico City and accessible by regional roads, the planned underground operation would produce an average of 5.4 million oz. of silver, 13,000 tonnes of lead and 29,000 tonnes of zinc annually over 18 years. Revenue from lead and zinc would help bring mine-site all-in sustaining costs to $15.06 per payable silver ounce, Endeavour estimates.
Self-financed
Endeavour expects to fund the majority of construction of Pitarrilla through a combination of cash on hand and cash flow from its operating mines. It ended September with $287.9 million in cash, about half the estimated construction cost. The spending would be spread over a 30-month construction period.
Pitarrilla has an estimated break-even silver price of less than $30 per oz., Endeavour said Thursday. The company realized $62.42 per oz. on third-quarter silver sales, it said last week in its third-quarter report.
National Bank analyst Alex Terentiew agrees with Endeavour’s assessment. Even at current spot metal prices of $3,600 per oz. gold and $42.50 silver, he predicts that Endeavour will keep a cash balance of at least $200 million over the development period, “leaving it with more than sufficient liquidity to advance the project on our schedule.”
Improved visibility
Endeavour’s new analysis replaces a 2009 underground prefeasibility study and a 2012 open-pit feasibility study with a current underground development plan, “materially improving visibility on capital, production and cash flow,” Terentiew said.
“In essence, today’s updated mine plan showcases a more targeted underground sulphide development strategy, representing a reduced operational footprint and a shift from the open-pit concept outlined in the 2012 feasibility study prepared by the previous operator,” CIBC mining analyst Cosmos Chiu said in a note.
Endeavour has approvals for underground development, mining and water use. It still needs a permit for its proposed dry-stack tailings site and other approvals and amendments, and its board has yet to make a construction decision.
Terentiew models first production in 2030, assuming that the tailings permit arrives in 2027 and construction starts in late 2027 or early 2028.
Endeavour shares dropped 1.8% to C$8.57 Friday morning in Toronto, valuing the company at about C$2.5 billion ($1.7 billion). The stock has traded between C$8.70 and C$20.70 in the past year.


Be the first to comment on "Endeavour’s $585M Pitarrilla plan faces silver slide"