
Highlander Silver (TSX, NYSE-A: HSLV) has hired Paris-based Natixis Corporate & Investment Banking to lead a proposed $330-million (C$465-million) seven-year senior secured debt financing for its Corani silver project in Peru.
The potential loan would be fully underwritten and supported by a cost-overrun provision of as much as $100 million to be arranged by Highlander before the first draw, the company said on Wednesday. Final amounts remain subject to due diligence and other approvals, with closing targeted for the first quarter of 2027. Highlander had about $100 million in cash and no debt at June 30.
“Importantly, Highlander Silver has retained 100% of the offtake rights to the project to preserve optionality and maximize future value amidst an intensifying global competition for clean concentrates,” President and CEO Daniel Earle said in a release.
The financing moves Highlander closer to funding construction at Corani, a fully permitted project in Peru’s Puno region containing 229 million oz. silver in proven and probable reserves. An updated feasibility study is expected this year and is to include revised reserves and resources as well as details of Highlander’s staged approach to development.
No equity
“We estimate the build will require $450-$500 million of capex, and expect a revolving credit facility will be put in place to satisfy the cost overrun requirement, negating the need for equity financing,” BMO Capital Markets mining analyst Kevin O’Halloran said in a note.
Highlander is approaching fully funded status for Corani, with about $100 million already in the bank and its operating Mercedes gold-silver mine in Mexico expected to contribute roughly $100 million during 2027 and 2028 under BMO’s commodity-price assumptions, O’Halloran said.
BMO expects construction to begin in the first half of 2027 and first production by the end of 2029.
Scotiabank similarly estimates initial capital spending at about US$460 million. The proposed Natixis loan would therefore cover roughly 72% of construction costs, broadly in line with the bank’s previous assumption that about 70% of Corani’s initial capital would be debt funded, analyst Eric Winmill said.
Staged development
Corani’s 2019 feasibility study outlined a 15-year mine producing an average 9.6 million oz. silver annually. At $18 per oz. silver, it estimated initial capital of $579 million, an after-tax net present value at a 5% discount rate of $532 million and a 23% internal rate of return. Life-of-mine all-in sustaining costs were pegged at $4.55 per oz. silver.
Corani holds 138.6 million proven and probable tonnes grading 51.3 grams silver per tonne, 0.9% lead and 0.55% zinc for 229 million oz. silver, 2.7 billion lb. lead and 1.7 billion lb. zinc. The reserve estimate dates from November 2019.
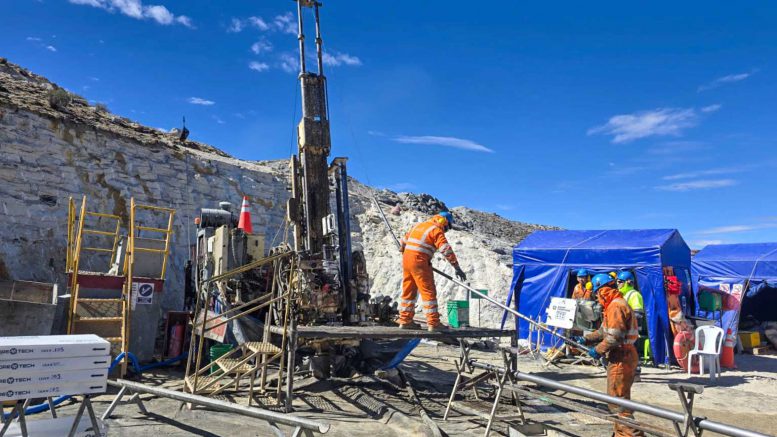
Highlander has already begun site work at Corani, including camp construction, preliminary earthworks and road building. The workforce had grown to more than 300 people by July, the company said.
Bear Creek
Corani came to Highlander through its Bear Creek deal completed in February. The company issued about 36.2 million shares to acquire the Bear Creek stock it didn’t already own.
The transaction also brought the Mercedes gold-silver mine in Mexico into Highlander’s portfolio alongside its San Luis gold-silver project in Peru.
Highlander shares fell 7% to C$7.62 Wednesday morning in Toronto as silver prices dropped about 3% and wider markets fell on rising bond yields. The company has a market capitalization of C$1.55 billion ($1.1 billion).
Be the first to comment on "Highlander lines up $330M Corani silver project debt"