
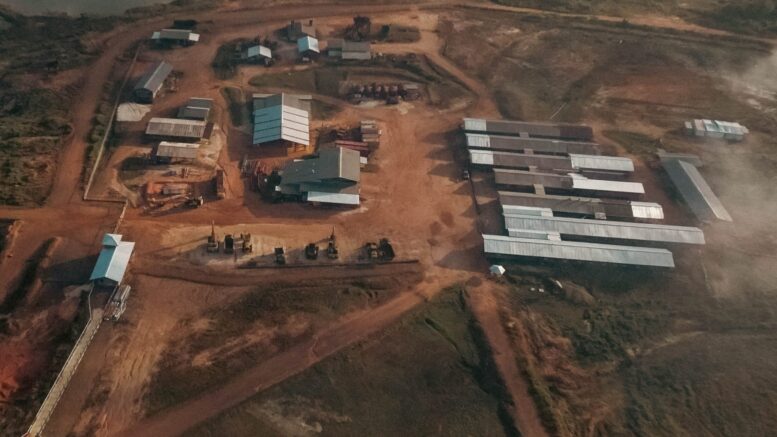
Aris Mining (TSX, NYSE: ARIS) raised the estimated construction cost of its Toroparu gold project in Guyana by 36% to $1.1 billion (C$1.6 billion), while extending its operating plan and maintaining an early 2027 target for a construction decision.
The prefeasibility study, released after markets closed Thursday, outlines 5.6 million oz. of gold production over 29 years of processing, including 258,000 oz. annually in the first 17 years. BMO and National Bank mining analysts said the larger project helps offset the higher capital bill. The earlier plan outlined 5 million oz. over 21 years. The revised schedule includes 21 years of mining.
“We currently estimate that the company will be able to internally finance the remaining capital required through its existing cash flow,” BMO mining analyst Brian Quast said Friday in a note.
Toroparu would add a major producing asset in Guyana to a company expanding its Colombian mines towards combined annual output of 500,000 oz. The next hurdle is permitting: Aris needs a large-scale mining licence and other approvals before committing to a 32-month build.
Detailed engineering
Construction capital, including contingency, has risen by $299 million from the $820 million estimated in the 2025 preliminary economic assessment. The new plan replaces an owner-operated leased mining fleet with contractors.
More detailed engineering, a longer construction schedule in a remote location, expanded infrastructure and industry inflation contributed to the increase, National Bank mining analyst Don DeMarco said in a note Thursday. Greater production early in the operating life and lower sustaining capital support the revised economics, he said.
The result is “a more conservative, execution-ready baseline fully offset by front-loaded production and stronger project economics,” DeMarco wrote.
DeMarco maintained an outperform rating and C$39 share-price target. Quast kept his outperform rating and C$48 target while lifting BMO’s valuation of Toroparu to about $2.1 billion from $1.9 billion.
Funding and returns
The company’s initial funding requirement is $1 billion. That includes $1 billion of construction capital, $102 million of contingency and $24 million of working capital, less $138 million assumed to be available under an existing precious-metals streaming agreement with Wheaton Precious Metals (TSX, NYSE, LSE: WPM). The streaming funds remain subject to Wheaton electing to proceed. The companies are exploring amendments to the agreement.
BMO expects cash generation from existing operations to cover the balance. DeMarco also pointed to liquidity, unused borrowing capacity and cash flow expected from the Marmato expansion. Aris continues to target first gold from Marmato’s new carbon-in-pulp plant in December.
At a gold price of $3,600 per oz., Toroparu has an after-tax net present value of $2.8 billion at a 5% discount rate, a 32% internal rate of return and a 2.2-year payback from the start of operations. At the same gold price, the earlier assessment’s valuation was about $2.7 billion, DeMarco said.
The earlier study’s published base case used $3,000 gold, so its headline $1.8-billion valuation is not directly comparable. At $3,000 gold, the new study also values Toroparu at about $1.8 billion.
Toroparu’s average production is expected to reach 291,000 oz. annually over the first five years. Output is projected to average 195,000 oz. over the full processing life as lower-grade stockpiles enter the plant later in the schedule. Life-of-project all-in sustaining costs are pegged at $1,494 per oz., up from $1,289 previously, while estimated sustaining capital fell 57% to $459 million, DeMarco said.
Larger resource
The study also establishes Aris’s first reserve estimate for the project. Toroparu is estimated to hold 200.2 million proven and probable tonnes grading 0.92 gram gold per tonne for 5.92 million oz. of contained gold.
The resource contains 360.9 million measured and indicated tonnes at 0.80 gram gold per tonne for 9.25 million oz., inclusive of reserves. Another 115.4 million inferred tonnes at 0.68 gram gold contain 2.54 million oz.
The 74% increase in measured and indicated gold reflects a higher resource gold price, lower cut-off grades and the inclusion of lower-grade material, DeMarco said. The resource uses $2,600 gold, compared with $1,950 previously. The new reserve estimate uses $1,950 gold.
Toroparu lies about 215 km southwest of Georgetown, in Guyana’s Cuyuni-Mazaruni region, according to Aris’s annual information form. The company applied for its large-scale mining licence in August.
Aris shares rose 0.1% to C$21.11 Friday morning in Toronto, valuing the company at about C$4.4 billion. The stock has traded between C$14.98 and C$31.47 over the past year.



Be the first to comment on "Aris extends Toroparu gold plan as cost climbs 36%"