
Canada spent the first half of September answering Washington’s trade escalation dollar for dollar after the United States imposed 50% tariffs on a broad range of Canadian goods that extend well beyond the stated grievances of autos, dairy and alcohol.
The country’s counter-tariffs on $19.7 billion (C$27.6 billion) of U.S. imports took effect Sept. 8 and this week the same government hosted the first Canada Investment Summit in Toronto, putting a 167-project prospectus in front of investors managing a suspiciously rounded $100 trillion.
American managed money, rather uncomfortably, accounted for the bulk even with the world’s richest sovereign wealth funds in the same room. Ottawa has been tight-lipped, but leaked reports count about $360 billion in pledges. Mining is the largest category by number with 63 entries, but cheap at the price of a little over $53 billion required.
Mining is dwarfed by mega projects like the C$57-billion expansion of the ice-free-for-four-months-of-the-year Port of Churchill, a C$44-billion offshore wind farm off Nova Scotia to slow global warming (something those advocating for Churchill may want to work into their base case), and a C$25-billion oil pipeline to the Pacific that would have to succeed where Northern Gateway did not.
Sitting on gold mines
Three gold projects have confirmed they are in the book: Troilus Mining’s (TSX: TLG; US-OTC: CHXMF) Troilus project in Quebec, NexGold Mining’s (TSXV: NEXG; US-OTC: NXGCF) fully permitted Goldboro in Nova Scotia, and Canagold Resources’ (TSX: CCM; US-OTC: CRCUF) New Polaris in British Columbia. They belong to an entirely different category from the tentpole projects.
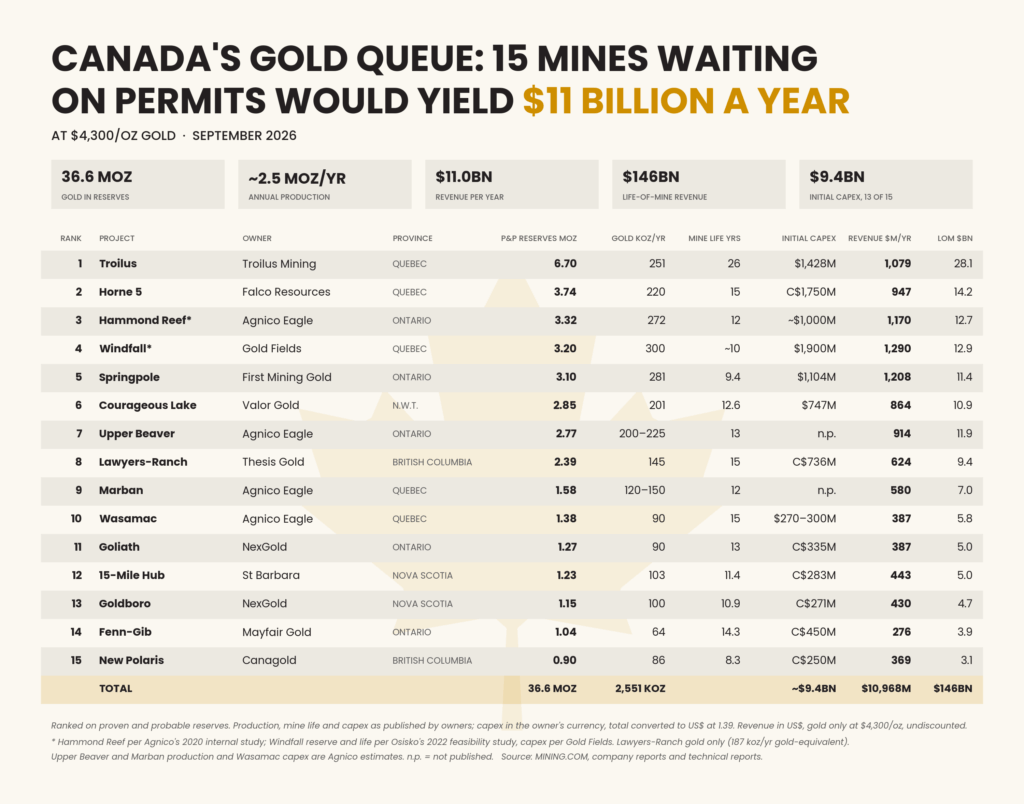
These, and a dozen other Canadian gold projects we looked at, have mine plans and declared reserves, the capital required is barely in double-digit billions, the studies are done, and in five cases the only thing between the owner and a construction decision is one government signature.
At today’s gold price they would produce a shade under $11 billion a year in revenue on an initial capital bill of $9.4 billion from 13 published numbers (and another billion-odd estimated for the remaining two).
That’s enough to buy almost 50 medium icebreaker escorts, hook up a third of the nacelles (depending on prices for rare earths, which Canada is still attempting to mine) needed for stage one of Wind West and a decade’s worth of ESG red tape and lawsuits for the pipeline.
Duty-free
Gold is the one major Canadian export for which the American market is optional. Bullion enters the U.S. duty-free, and that status was even reaffirmed by a Trump executive order last September when Swiss kilobars were slapped with a 39% duty after a customs cock-up.
In any case, it does not need the American market: doré poured in Canada is refined and sold into London and Zurich at the same price on the same day.
At roughly US$4,300 per oz., Canada’s 213 tonnes of 2025 mined output ranked fourth in the world and was worth close to $30 billion. The question this piece asks is how much more is sitting in the permitting queue and how quickly it could fill Canadian coffers.
We screened Canada’s gold development projects for three things: a prefeasibility or feasibility-level mine plan, which under CIM rules is the minimum for declaring a mineral reserve; a meaningful reserve; and no construction decision taken.
That last test drops some of the country’s most talked-about projects. Kinross Gold’s (TSX: K; NYSE: KGC) Great Bear was fast-tracked by Ontario in February but is still at PEA stage with no reserves. Agnico Eagle Mines (TSX, NYSE: AEM) greenlit the $2.4-billion Hope Bay mine in May.
Osisko Gold Group (TSXV, NYSE: OGG) took the construction decision on Cariboo on Sept. 14, the morning the summit opened. Talamore Mining’s (TSX: TALA; US-OTC: TALMF) Coffee project in Yukon is building its access road ahead of a feasibility study due in the fourth quarter.
Fifteen projects survive, ranked by contained gold in proven and probable reserves, a measure of scale rather than value. New Polaris, at the bottom of the list, grades 9.94 grams gold per tonne, while Hammond Reef, near the top, grades 0.84 gram.
Together they hold 36.6 million oz. in reserves. Using the owners’ published production profiles, or their internal estimates where no study exists, they would produce around 2.5 million oz. a year at steady state, roughly 78 tonnes, or a 35–40% increase on Canada’s current output. At a US$4,300 gold price, the owners’ projected life-of-mine output would have a gross metal value of about $146 billion.
Crown achievement
For a country counting tariff losses, quick wins before the trade winds change direction again should be a no-brainer. Gold mines are unusually good taxpayers. On top of the 26.5% corporate rate every other industry pays, a mine pays a provincial mining tax or duty on profit first, taking the combined government share of its operating margin to roughly 34% in Ontario, 37% in B.C. and the Northwest Territories, 40% in Nova Scotia and 42% in Quebec.
Using an industry-average cost of US$1,800 per oz. and a US$4,300 gold price, the 15 projects would send on the order of $2.4 billion a year to federal and provincial treasuries, and something like $33 billion over their lives, about half of it to Quebec. Those are mature-year figures because a new mine writes off its construction capital before paying meaningful income tax, so the early years yield far less. All the more reason to start blasting sooner rather than later.
The C$2.4 billion is also a good chunk of what Finance Canada could raise from counter-tariffs, or put another way, how much more Canadians have to fork out for the same things they wanted up until Sept. 7. Those doing their patriotic duty by forgoing Jack and Coke want to know.
Best laid plans
First gold pours at these projects cluster towards the end of the decade: Windfall in 2029 if its Quebec approval lands this year; Troilus, Springpole, Upper Beaver and Fenn-Gib around 2030; Goldboro as early as 2028; and Marban and Wasamac in 2033-34. Almost all of those are management targets, or, if we must import corporate speak from softer industries, “aspirational,” rather than study schedules.
The construction periods behind them are short, one to three years, but in Canada’s permitting hell that hardly matters. S&P Global found mines that started up between 2020 and 2023 took an average of 17.9 years from discovery to first production, up from 12.7 years for mines that started in 2005-09. Much of the stretching out came in exploration, permitting and studies, and in the wait between feasibility and construction. A broader S&P study put gold mines at 15.2 years (yes, only).
Canada, in a separate S&P comparison, was among the slowest countries in the world at 27 years. Not to put too fine a point on it, but that’s hitting pay dirt under Jean Chrétien and still waiting to be paid for dirt under Mark Carney.
PwC’s Mine 2026 report puts the Canadian figure at about 20 years to permit and build, six more than Australia. Australia’s general U.S. tariff is 12.5%, though some sectoral tariffs are higher, and Prime Minister Anthony Albanese has ruled out retaliatory tariffs. Same insult, less injury.
Waiting room
Several projects on this list are already deep into that two-decade clock.
Gold Fields’ (JSE, NYSE: GFI) Windfall has a Cree agreement, 12 km of underground workings and a US$1.9-billion budget, and has been waiting since the first quarter for a COMEX decision. Falco Resources’ (TSXV: FPC; US-OTC: FPRGF) Horne 5 has a three-month-old feasibility study and Glencore’s (LSE: GLEN) smelter next door, and is waiting on a Quebec decree. First Mining Gold’s (TSX: FF; US-OTC: FFMGF) Springpole cleared its federal review in June, eight years after the process began, and is now waiting on Ontario.
Agnico Eagle’s Hammond Reef has both federal and provincial environmental approvals and, on Agnico’s own 2020 numbers, would produce a glittering 272,000 oz. a year; the company says it is not approved for development. Upper Beaver, Marban and Wasamac are on a schedule that runs to 2033.
How much of that is Agnico’s own sequencing and how much is its read on how long the remaining permits will take is Agnico’s to say. What the numbers say is that a single company holds a quarter of the queue, and that its earliest-permitted project is the one with no date attached.
Dead in the water
Our 15 projects may well prosper soon, but examples of Canadian permit peril and regulatory ruin are not hard to find.
Take Taseko Mines’ (TSX: TKO; NYSE-A: TGB) Prosperity copper-gold deposit at Fish Lake, one of the largest undeveloped in the country. It received British Columbia’s environmental certificate in January 2010. Ottawa rejected it that November over the plan to use a lake called FISH Lake for tailings (sounds bad, sure, but Taseko was going to build a new lake with all 85,000 rainbow trout relocated).
Taseko redesigned it, resubmitted it as New Prosperity, and was rejected again in February 2014. Four months later the Tŝilhqot’in Nation won the Supreme Court title case that reset the ground rules for the whole region.
A decade of litigation followed, ending in June 2025. Taseko gave up and B.C. forked over C$75 million. Sixteen years after the provincial approval, the deposit is still in the ground and nobody is proposing to do anything in the area other than fly fishing.
Don’t bother
NexGold’s Goldboro, which just yesterday said early works are now under way, is the exception that proves the rule. Fully permitted, with a Crown lease and a Mi’kmaq benefits agreement, it is waiting on financing and a final construction decision rather than another permit signature. It is easy to blame permitting (guilty as charged) for the inertia in Canada’s mining industry, but TSX Venture juniors still have to raise the capital.
The Productivity Mega Deduction (a name which veers into Big Beautiful Bill territory at a time Canada is trying to distance itself from bluster from the south) will help build mines, but the ambitions of the summit’s marquee vehicle, the C$50-billion Maple Fund launched by CPP Investments and Brookfield Asset Management (TSX, NYSE: BAM), are too lofty for the grassroots.
The fund is looking for opportunities with more than C$5 billion of project equity. Not one of the 15 gold projects clears that bar and six of them need less than C$500 million each: the kind of cheque that the MF cannot be bothered to write.
Even the most expensive gold mine ever built in the country, Iamgold (TSX: IMG; NYSE: IAG) and Sumitomo Metal Mining’s (TSE: 5713) Côté in Ontario, came in at a billion below. And that was after a C$2.3-billion budget blowout.
The rest of the list is earlier. Thesis Gold & Silver’s (TSXV: TAU; US-OTC: THSGF) Lawyers-Ranch, Mayfair Gold’s (TSXV: MFG; NYSE-A: MINE) Fenn-Gib, St Barbara’s (ASX: SBM) 15-Mile hub and Canagold’s New Polaris all entered environmental review or the formal permitting process in the past year. Valor Gold’s (TSX: VGC; US-OTC: VLGDF) Courageous Lake has not applied.
Queue the fast track
Canada now has four fast-track mechanisms that matter here: the federal Major Projects Office, Ontario’s One Project One Process, Quebec’s new Filon stream and B.C.’s priority list. Two of the 15 are on one of those tracks: Troilus in Filon and New Polaris on B.C.’s priority list. The other 13, including Windfall, Horne 5, Hammond Reef and Springpole, are on the standard track.
Carney told reporters after the summit that the standard would now be “one project, one review, one year.” But much like those pesky interprovincial barriers Carney says cost “up to $200 billion” a year and promised to sweep away with “one Canadian economy, not 13,” it is often in the provinces that the fast track goes off the rails. The barriers have yet to disappear no matter how loudly Trump’s tariffs are derided from podiums.
Provinces control much of the review, and the 15 show where the test lies: Quebec holds the decisions on Windfall and Horne 5, Ontario on Springpole, and Agnico’s four sit in both. The projects are known, studied and in several cases already approved by one level of government.
Everything on the table is at $4,300 per oz. The banks still think that is low. J.P. Morgan Global Research’s public June forecast has gold averaging $6,000 in the fourth quarter of 2026 and reaching $6,300 by the end of 2027. Wells Fargo Investment Institute cut its targets in August to $4,900-$5,100 for the end of 2026 and $5,400-$5,600 for the end of 2027. Goldman Sachs, after trimming, still has $4,900 for year-end.
Ottawa, you can do the math.
Be the first to comment on "Comment: Gold is tariff-proof. Canada has $11 billion a year of it stuck in permitting "